Every month we see huge developments and changes happening in the banking industry. In September, IBM released research suggesting that 65% of banks have plans to put blockchain projects in production in three years’ time. Meanwhile the CMA recently released findings stating that banks are not working hard enough for their customers, and the BBC claims more than 600 High Street bank branches have closed in the UK in the past year. On top of this, traditional retail banks are facing increasing competition from digital-first challenger banks such as Monzo (formerly Mondo) and Atom.
The changes aren’t just coming from within the industry, but also from a huge shift in customer expectations. 51% of US adults bank online, as do 47% of Europeans, and this number is likely to increase as more Millennials buy in to financial services. This is part of a wider customer attitude that banks should be using the latest popular technology to provide the best service to their customers. However, with new expectations and technologies emerging all the time, how can the banking industry adapt to this digital world?
IBS Intelligence is the definitive source of news, analysis and thought leadership relating to global banking and financial technology markets. We cover what is really going on – the good, the bad, the lessons, the mistakes and the masterstrokes, with no advertorial or marketing hype. IBS Intelligence Blog is an excellent outlet to voice opinions, views and share ideas about all things fintech, and editorial contributions are welcome!
Showing posts with label banking. Show all posts
Thursday, 13 October 2016
Wednesday, 21 September 2016
imaginBank: Simpler banking for the digital age
"I don’t need an elaborate banking service with branches, passbooks, letters in the post, an annual financial review and a bank manager that knows my name. Interest? I don’t save enough to accrue any, or I put my money somewhere else. All I really want is an account that will accept my deposits, hold my money and release it when I want to make a payment or transfer. I don’t want to wait for transactions to appear on my balance or for transfers to clear. An automatic payment function would be useful, so I can settle my bills easily. But most important of all, I want to do everything, repeat everything, on my phone. Some exclusive offers and deals would be good too. That’s it."
Welcome to the mindset of a growing demographic of today’s banking customers. All are committed device users - not power users or early adopters - just people that manage their lives using phones and tablets. Many are young – Millennials - but not all. Most have modest incomes and are determined to live debt-free and unconstrained by financial commitments.
Friday, 20 May 2016
Rising to the challengers
Challenger banks have been a black cloud looming over the “big four” for the past few years. The traditional High Street banks have been braced for these challengers to shake things up and create an entirely new environment, just as budget airlines did to the aviation industry in the nineties. And with the UK’s FCA keen to see consumers benefit from “effective competition” for regulated financial services, the time seems right.
While those working in the industry are tracking every move of the challengers and what they offer, this awareness has yet to filter down to customers. With the big four still holding over 90% of the UK market, and consumer awareness of challenger brands failing to gain momentum, is the impending shake-up going to happen, and if so, when?
Wednesday, 4 May 2016
Robo-advisors – as revolutionary as they seem?
The rise of the robo-advisor has been well documented over the past year or so. The FCA recently announced an Advice Unit that helps firms develop robo-advisor models, and RBS has also publicised that they will be sacking hundreds of face-to-face advisors in favour of robots.
Armed by what appears to be a cheaper, more accessible service, the likes of Nutmeg and Wealthfront have not been shy in their promotion of being at the forefront of opening up obtainable investment opportunities to a wider audience.
Tuesday, 1 March 2016
Cash continues to make a splash
Look away now, banks, card schemes and all the other proponents of a cashless society. It seems that notes and coins are not going away just yet. LINK cash withdrawals from UK ATMs in 2015 amounted to a record £128 billion. The total number of cash withdrawals only grew slightly in 2015 (by 0.8%) with the value of these increasing by 2%. The amount cash machine users took out also went up – with the average value rising from £61.25 in 2014 to £61.93 in 2015.
Monday, 22 February 2016
FinTech Future: It's Burgers, not Bitcoins
The other day I was watching my daughter playing with a
group of children at her nursery. I didn't quite follow the rules but it was a
picture card game with the apparent objective of winning as many cards as
possible.
After a short while a couple of smug-looking kids (you know
the sort!) had mastered the game and accumulated the majority of the cards to
the obvious disdain of the rest, including my daughter.
Wednesday, 10 February 2016
Challenges to implementing dynamic pricing in financial services
The roadblock to real pricing execution lies in bank legacy core systems. Just a reminder, legacy systems are costly. A study by IBM suggests that rigid legacy systems cost the industry $200 billion annually, and siphons off roughly 20% of pre-tax profits.
Let that sink in for a moment.
Friday, 5 February 2016
The strategic importance of dynamic pricing in financial services
At its foundation, dynamic pricing is simply flexible pricing based on current market demands for a particular product or service. It is second nature to the hospitality and travel industries, even the retail goods market, where algorithms account for competitive pricing, supply and demand, time of day, and on-demand service spikes to affect an ever-changing real time price and profit margin.
But in banking, dynamic pricing is a different story: more of a Utopic dream than a reality, with some nuances unique to the industry.
Friday, 22 January 2016
Banking is a battlefield
- For anyone who wasn’t around for the 80s, any karaoke bar experience virtually guarantees that the Pat Benatar tune 'Love is a Battlefield' comes to mind when anything is called a 'battlefield': banking included.
Sad thing is, when it comes to core banking systems, legacy status means any claim of 'we are young, we are strong, no one can tell us we’re wrong' is laughable at best, an utter lie at worst.
Wednesday, 20 January 2016
A common banking disease that can lead up to $67bn loss in a year: fraud
Fraud is big business, costing the banking industry $67 billion per annum, according to the Association of Certified Fraud Examiners. It’s a problem no one can afford to ignore as firms struggle to recover from the global financial crisis and the world’s major economies teeter on the edge of recession. Most worrying of all, its incidence is escalating.
NetGuardians has recently partnered with Temenos to compile a comprehensive e-book, A-Z of Banking Fraud 2016. This e-book outlines the what, why and how of fraud; exploring the size of the issue, who commits it and, most importantly, what can be done.
Thursday, 26 November 2015
Video banking: the best of both worlds
OK, so video banking is not the latest trend, and a number of banks around the world have been offering it for some time now (the Polish market has been particularly prolific – think Idea Bank, Alior Bank, ING and Raiffeisen).
It is a very important channel – as it offers actual human contact in the increasingly faceless mobile banking world and thus shouldn’t be neglected.
It combines the best of both worlds – modern technologies and human interaction.
Thursday, 15 October 2015
Do we need the digital-only bank?
Post-crisis a lot of people don’t trust banks. You can’t really
blame them, it’s just the way things are now. That mistrust hasn’t stopped people
using their banks, of course – where else would they keep their money? Apart
from stuffing it into the mattress there isn’t much choice.
Never fear,
those of you clamouring for a different way to do banking (raise your hands –
anyone?), as a wave of digital-only banks have arrived to save the day.
Wednesday, 30 September 2015
The 'Pay' model is strong but the banks are still in play
The big guns
– Apple, Samsung and Google – are dominating the mobile payments news cycle now
that their respective ‘Pay’ platforms threaten to disintermediate the world’s
banks.
They won’t have it all their own way, though; banks are responding with their own platforms. But is it too little, too late?
Thursday, 28 May 2015
Times of change
The pace of change in the financial services sector seems unprecedented. Traditional business models are being dismantled at a rate that, for inflexible incumbents, must be alarming. It is not solely that enabling technology is hurtling forwards, it is also to do with the bigger picture of low margins, heightened customer expectations and increased competition.
Thursday, 13 November 2014
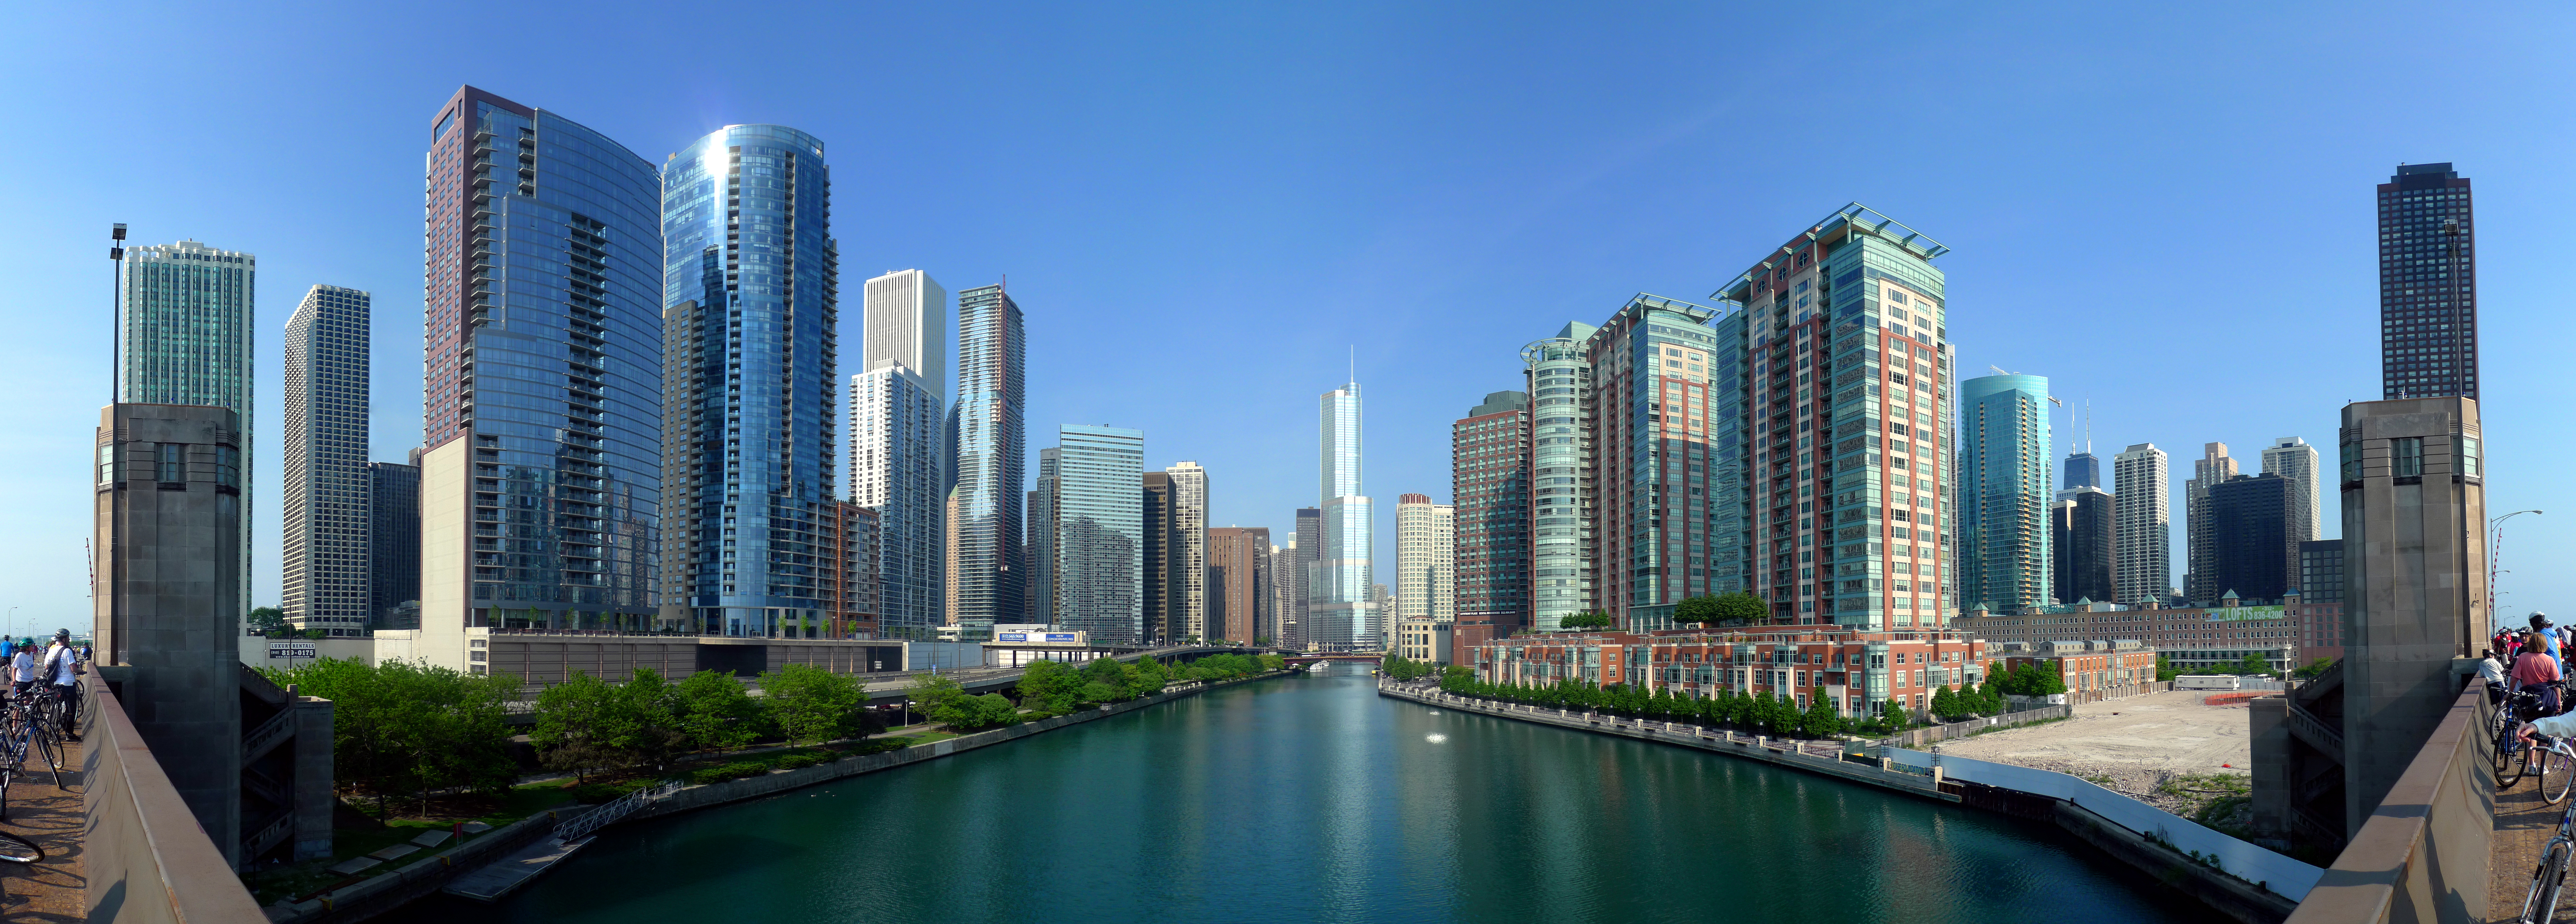
BAI Retail Delivery 2014: the inside track
![]() |
| BAI Retail Delivery, Chicago. Source: wikipedia |
Tuesday, 7 October 2014
Branches and mobile banking: do you need both?
![]() |
| © www.visionaustralia.org |
Friday, 3 October 2014
Wednesday, 1 October 2014
Sibos: day two round-up
Tuesday, 30 September 2014
Sibos: day one round-up
![]() |
| @Swift |